Tenant screening is one of the most important parts of renting out a property.
A good screening process can help you find a tenant who pays rent on time, follows the lease, communicates clearly, and takes care of the property.
A bad screening process can lead to confusion, inconsistent decisions, fair housing problems, unpaid rent, disputes, or avoidable denials.
If you’re a small landlord or first-time rental property owner, screening can feel tricky. You want to protect your property, but you also want to treat applicants fairly.
You may be reviewing income, credit, rental history, tenant screening reports, references, pets, co-signers, and application details all at once.
The goal isn’t to find a perfect tenant. Perfect tenants don’t exist.
The goal is to create a screening process that’s clear, consistent, documented, and tied to real rental risk.
Why Tenant Screening Matters
Tenant screening helps landlords make informed rental decisions.
When someone applies to rent your property, you’re deciding whether they’re likely to pay rent, follow the lease, and care for the home. Screening gives you information that can support that decision.
A tenant screening process may include reviewing:
- Income
- Employment or income stability
- Rental history
- Credit history
- Tenant screening reports
- Prior landlord references
- Eviction-related records
- Rental debt
- Criminal background information, where allowed
- Identity information
- Co-signer or guarantor support
- Application completeness
The mistake many landlords make is focusing too heavily on one piece of the application.
Credit matters, but credit isn’t everything. Income matters, but income isn’t everything. A landlord reference can be helpful, but it may not tell the full story either.
A stronger process looks at the full application and applies the same standards to each applicant.
Start With Written Screening Criteria
Before you accept applications, write down your screening criteria.
This is one of the best things a landlord can do.
Written criteria help you avoid making decisions based on emotion, assumptions, or “gut feeling.” They also make it easier to explain your process if an applicant asks why they were denied, approved, or approved with conditions.
Your criteria may include:
- Minimum income requirement
- Accepted proof of income
- Rental history requirements
- Credit history standards
- Treatment of collections
- Treatment of rental debt
- Eviction-related record policy
- Co-signer or guarantor policy
- Pet policy
- Occupancy standards
- Application completeness
- Required identification
- Required references
Your criteria should be specific enough to guide decisions, but not so rigid that they ignore useful context.
For example, instead of writing:
“Must have good credit.”
A clearer standard might be:
“Credit history will be reviewed as part of the full application. Recent unpaid rental debt, current past-due accounts, or unresolved collections may require additional documentation or may result in denial under the screening criteria.”
That gives you more structure and helps applicants understand what matters.
Apply the Same Criteria to Every Applicant
Consistency is the heart of fair tenant screening.
If you ask one applicant for proof of income, ask all applicants for proof of income. If you require rental references, apply that requirement consistently. If you allow co-signers, make sure your co-signer policy is clear and available to applicants in similar situations.
Avoid making exceptions based on personal preference.
For example, don’t apply stricter credit standards to one applicant because they “feel risky,” while giving another applicant a pass because they seem friendly. Don’t ask one family for extra documentation while skipping the same step for another applicant with a similar profile.
Consistent screening helps protect both you and the applicants.
It also makes your process easier to manage.
Screen the Application, Not Your Assumptions
A rental application should be judged on relevant information, not assumptions about the person applying.
Focus on things that connect to the rental decision:
- Can the applicant afford the rent?
- Did they submit complete information?
- Can they document income?
- Do they have rental history?
- Are landlord references available?
- Are there unresolved rental debts?
- Does the tenant screening report show issues that need review?
- Is there a co-signer, if allowed and needed?
- Does the application meet your written criteria?
Avoid assumptions based on name, family status, appearance, disability, accent, age, background, or where someone comes from.
Good screening is boring in the best way. It follows the same steps every time.
Follow Fair Housing Rules
Landlords need to understand fair housing rules before advertising, showing, screening, approving, denying, or negotiating rental terms.
In general, housing discrimination based on protected characteristics is illegal. Federal protected categories include race, color, national origin, religion, sex, familial status, and disability. State and local laws may include additional protected categories.
This matters in tenant screening because even neutral-sounding practices can create problems if they’re applied inconsistently.
Avoid:
- Asking different applicants different screening questions without a clear reason
- Suggesting that certain applicants would be “a better fit”
- Steering families with children away from certain units
- Refusing reasonable accommodation requests without proper review
- Advertising in a way that describes the type of person you prefer
- Making exceptions for some applicants but not others
- Using vague reasons like “not the right fit” instead of documented criteria
Better approach:
- Write clear criteria
- Apply the same process
- Keep records
- Focus on the application
- Avoid personal assumptions
- Get local guidance when unsure
Fair housing rules are one reason written screening criteria matter so much.
Verify Income Carefully
Income is one of the most important parts of tenant screening.
A tenant may have great credit, but if the rent doesn’t fit their income, the lease may still become stressful. Another applicant may have imperfect credit but strong income and good rental references.
Many landlords use an income rule, such as 2.5x or 3x the monthly rent. If you use a rule like that, state it clearly and apply it consistently.
Accepted proof of income may include:
- Pay stubs
- Employment verification
- Job offer letter
- Bank statements
- Tax returns
- W-2 forms
- 1099 forms
- Profit-and-loss statement
- Benefit award letters
- Pension or retirement income statements
- Court-ordered support documentation, if the applicant wants it considered
Be thoughtful about applicants who don’t have traditional pay stubs.
Self-employed renters, gig workers, contractors, retirees, students, people starting new jobs, and people with benefit income may need to document income differently.
If you accept alternate income documents, write that into your criteria.
Understand Gross Income vs. Take-Home Pay
Many landlords use gross income, which is income before taxes and deductions.
Applicants, however, pay rent from take-home pay. That means someone may technically meet a 3x rent rule but still feel stretched if they have high debt payments, insurance costs, childcare, or other obligations.
As a landlord, you may not review a tenant’s full personal budget. But you can use income requirements as one part of the bigger screening picture.
If income is close to the minimum, you may consider whether your policy allows:
- Proof of savings
- A co-signer
- A lower-rent unit
- Additional documentation
- Strong rental references
- Manual review
Whatever you allow, keep it consistent.
Review Credit Without Relying Only on the Score
Credit can be useful, but a credit score alone may not tell the full story.
A lower score may come from medical bills, old collections, high credit card balances, temporary unemployment, divorce, identity theft, or limited credit history. A higher score may still hide rental concerns if there’s unresolved rental debt or poor references.
When reviewing credit, look at the details.
Credit issues that may matter include:
- Recent missed payments
- Accounts currently past due
- Unpaid collections
- Rental debt
- Utility collections
- Charge-offs
- Bankruptcy
- High balances
- Several recent applications
- Accounts that appear inconsistent with the application
Rental-related credit issues may deserve closer review because they connect directly to housing.
For example, unpaid rent owed to a prior landlord may be more relevant than an old medical collection. A utility collection may matter if the tenant will be responsible for utilities. A collection that’s paid and documented may be different from one that’s recent and unresolved.
Credit should help you ask better questions. It shouldn’t replace the full application review.
Treat No Credit Differently From Bad Credit
No credit and bad credit are not the same.
Bad credit usually means negative information appears in the credit history. No credit usually means there isn’t enough history to review.
No-credit applicants may include:
- First-time renters
- Students
- Young adults
- People new to the U.S.
- People who use cash or debit
- People recently divorced or separated
- People who haven’t used credit in years
If you automatically deny no-credit applicants, you may reject people who are financially responsible but haven’t used traditional credit.
You may choose to accept alternative documentation, such as:
- Proof of income
- Proof of savings
- Rental references
- Employment verification
- Utility payment history
- Co-signer or guarantor information
If you’re willing to review no-credit applicants, write that into your policy.
Rental History May Matter More Than Credit
Rental history is often one of the most useful screening factors.
A prior landlord may help you understand whether the applicant paid rent on time, followed the lease, communicated well, caused damage, or gave proper notice before moving out.
When checking rental history, you may ask:
- Did the applicant rent from you?
- What dates did they live there?
- What was the monthly rent?
- Did they pay rent on time?
- Did they follow the lease?
- Did they give proper notice?
- Were there complaints or violations?
- Did they leave owing money?
- Would you rent to them again?
Be careful with landlord references. Some prior landlords may not respond. Some may give minimal information. A current landlord may have an incentive to give a good reference if they want the tenant to move. A past landlord may be more candid.
Use references as part of the process, not the only decision point.
Watch Rental Debt Closely
Rental debt is one of the most important issues for landlords to review.
Rental debt may include:
- Unpaid rent
- Lease-break fees
- Move-out charges
- Damage charges
- Utility balances
- Late fees
- Cleaning fees
- Court-related costs
Because rental debt is directly tied to housing, it may be more relevant than other debts.
Before denying automatically, consider whether your policy allows review of:
- Amount owed
- Date of the debt
- Whether it’s paid or settled
- Whether it’s disputed
- Whether it belongs to the applicant
- Whether the applicant has documentation
- Whether there has been positive rental history since then
If you use a tenant screening report and the report shows rental debt, remember that reports can contain errors. The applicant may have the right to request the report and dispute inaccurate information.
Use Tenant Screening Reports Carefully
Tenant screening reports can help landlords review applicants, but they should be used carefully.
A tenant screening report may include:
- Credit information
- Rental history
- Eviction-related records
- Housing court records
- Criminal background information
- Identity information
- Income or employment information
- Screening scores or recommendations
If you use a screening company, understand what the report includes and how it’s generated.
Don’t rely blindly on a score or recommendation without reviewing the underlying information. A report may contain outdated, incomplete, duplicated, or inaccurate information.
For example:
- An eviction filing may not show that the case was dismissed.
- A debt may be listed even though it was paid.
- A record may belong to someone with a similar name.
- One court case may appear multiple times.
- A sealed or expunged record may appear incorrectly.
If you make a negative decision based on a consumer report, follow the adverse action notice process.
Understand Adverse Action Notices
An adverse action is not only a denial.
If you use a credit report, tenant screening report, or other consumer report to make a negative decision, you may need to provide an adverse action notice.
A negative decision may include:
- Denying the application
- Requiring a co-signer
- Charging a larger deposit
- Charging higher rent
- Offering different lease terms
- Taking another unfavorable action based on the report
The notice generally tells the applicant:
- Which company provided the report
- How to contact that company
- That they may request a copy
- That they may dispute inaccurate information
This is a key part of using screening reports responsibly.
Build adverse action notices into your process before you need them.
Be Careful With Criminal Background Screening
Criminal background screening can be complicated and may be affected by federal, state, and local rules.
If you review criminal records, your policy should be tied to legitimate rental concerns and applied consistently. Blanket policies can create legal risk, especially if they don’t consider the type of offense, age of the record, relevance to housing, or local restrictions.
Before using criminal background information, research your local rules or get qualified guidance.
If your screening company provides criminal background information, don’t assume every record should automatically result in denial.
Consider Co-Signers or Guarantors
A co-signer or guarantor may help reduce risk when an otherwise promising applicant has limited credit, lower income, or a weaker application.
If you allow co-signers, create a written policy.
Decide:
- When co-signers are allowed
- Whether co-signers are required in certain situations
- What income the co-signer must show
- Whether the co-signer’s credit will be checked
- Whether the co-signer signs the lease or a separate agreement
- What the co-signer is responsible for
- Whether the co-signer remains responsible after renewal
- Whether the co-signer can be removed later
Make sure co-signer requirements are applied consistently.
Also remember: if you require a co-signer because of information in a consumer report, that may be an adverse action.
Keep Application Fees Clear
If you charge an application fee, be clear about what it covers.
Applicants may want to know:
- The application fee amount
- Whether it’s refundable
- What screening report is used
- Whether a credit check is included
- Whether co-signers pay a separate fee
- Whether the unit is still available
- Whether other applications are pending
- What criteria will be reviewed
Clear fee communication builds trust and reduces disputes.
If you already know an applicant doesn’t meet a hard requirement, be careful about encouraging them to pay a fee anyway.
A transparent process helps both sides.
Document Every Decision
Good records are essential.
Keep records of:
- Written screening criteria
- Rental applications
- Application dates
- Screening authorizations
- Income documents
- Landlord reference notes
- Screening report results
- Applicant communications
- Approval decisions
- Conditional approval terms
- Denial reasons
- Adverse action notices
- Lease documents
- Deposit records
Be careful with sensitive information. Applications may contain Social Security numbers, financial documents, credit data, and personal details. Store documents securely and limit access.
Good records help you stay organized and support consistent decision-making.
Common Tenant Screening Mistakes
Tenant screening problems often come from lack of process.
Common mistakes include:
- No written screening criteria
- Changing standards from applicant to applicant
- Relying only on credit score
- Ignoring rental history
- Not verifying income
- Asking inappropriate personal questions
- Applying rules inconsistently
- Using tenant screening reports without adverse action notices
- Automatically denying no-credit applicants
- Treating all collections the same
- Ignoring applicant documentation
- Not checking local landlord-tenant rules
- Not keeping records
The solution is not to make screening complicated. The solution is to make it consistent.
Sample Tenant Screening Criteria
This is not legal advice, but here’s an example of plain-English screening criteria a landlord might adapt with local guidance:
“Applications are reviewed based on income, rental history, credit history, tenant screening information, references, and application completeness. Applicants must provide proof of income and complete all required application fields. Credit history is reviewed as part of the full application. Applicants with limited or damaged credit may provide additional documentation, such as proof of savings, rental references, proof of on-time rent payments, paid or settled account documentation, or co-signer information. Unpaid rental debt, false application information, or failure to provide required documentation may result in denial.”
The exact language should match your property, process, and local laws.
Sample Message to Applicants
Here’s a simple message landlords can use to explain the screening process:
Hi [Applicant Name],
Thank you for your interest in [property address]. Before applying, I wanted to share the basic screening process. Applications are reviewed based on income, rental history, credit history, tenant screening information, references, and application completeness.
Applicants should be prepared to provide proof of income, rental history, identification, and authorization for screening. If there are credit or rental history issues, applicants may provide additional documentation, such as proof of paid or settled accounts, rental references, or co-signer information if applicable.
Please let me know if you have any questions before submitting the application fee.
Thank you,
[Landlord/Property Manager Name]
This kind of message helps applicants understand the process before they pay.
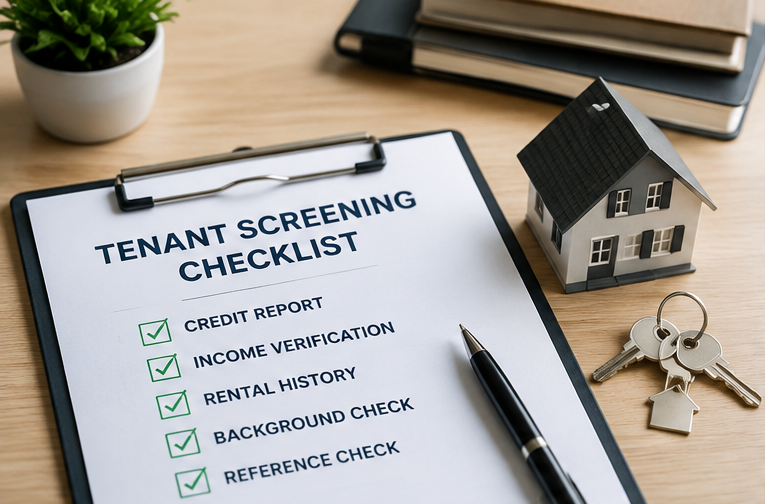
Quick Tenant Screening Checklist
Before approving or denying an applicant, ask:
- Did I apply written criteria?
- Did I use the same process for each applicant?
- Did I verify income?
- Does the income support the rent?
- Did I review rental history?
- Did I contact references, if required?
- Did I review credit details, not just the score?
- Did I check for rental debt?
- Did I consider documentation provided by the applicant?
- Did I follow my co-signer policy?
- Did I use a tenant screening report?
- Is an adverse action notice required?
- Did I document the decision?
A checklist helps keep the process fair and organized.
How to Really Screen Tenants Fairly: The Bottom Line
Tenant screening works best when it’s clear, consistent, and tied to real rental risk.
As a landlord, you don’t need to approve every applicant. You do need a process that helps you review applications fairly. That means writing screening criteria, verifying income, reviewing rental history, considering credit in context, using tenant screening reports carefully, following fair housing rules, and providing required notices when consumer reports affect negative decisions.
The goal isn’t to rely on one score, one report, or one feeling.
The goal is to make a careful, documented decision based on the full application.
Renters.help is built to help people understand rental approval, credit issues, tenant screening, and housing decisions from both sides of the application process.
Screening rental applicants and trying to understand credit, tenant reports, or adverse action notices? Renters.help can help make the rental application process clearer.